
Jasmine Birtles
Your money-making expert. Financial journalist, TV and radio personality.



 Ruby Layram
30th Sep 2026
Most people have heard of the FTSE 100, but its smaller sibling, the FTSE 250, is where many of Britain’s household names in travel, property, banking and construction live. And with UK shares still described by analysts as comparatively cheap, more beginners are asking how to get a slice. The easiest route is a FTSE 250 ETF.
In this guide you will learn what the FTSE 250 is, how it differs from the FTSE 100, the main FTSE 250 ETFs available to UK investors (with fees and yields), the risks, and exactly how to buy one.
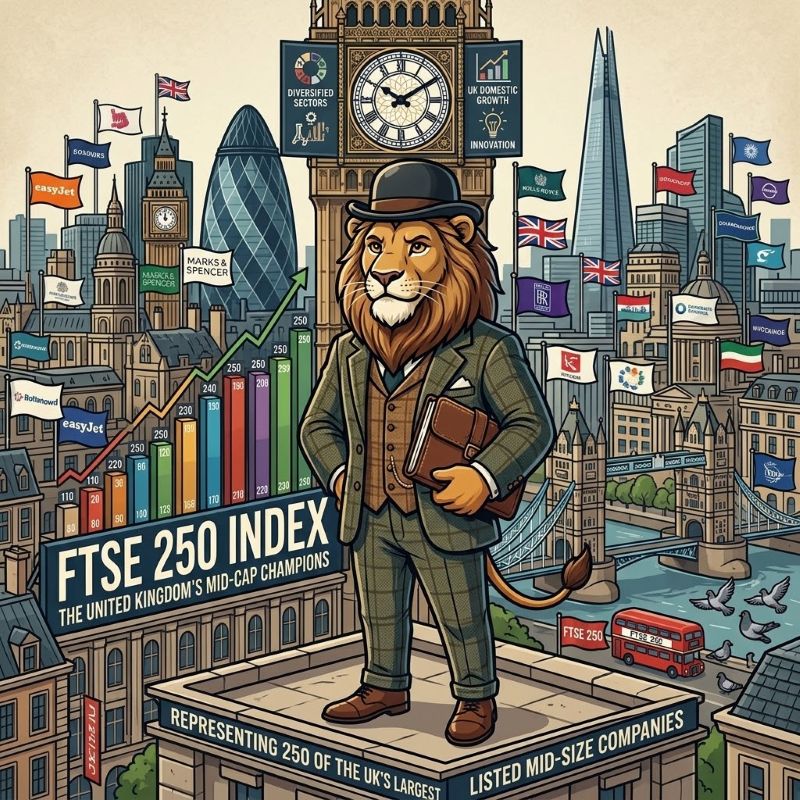
The FTSE 250 is an index (a list used to measure a slice of the stock market) of 250 medium-sized companies listed on the London Stock Exchange that rank just below the FTSE 100.
Think of the FTSE 100 as the big hitters, such as AstraZeneca, Shell and HSBC, and the FTSE 250 as the next tier up-and-coming or established mid-sized firms. You may know some of them: easyJet, WPP, Rightmove and Balfour Beatty are among the largest holdings in one popular fund.
An ETF (exchange-traded fund) is a basket of investments you buy in one go on the stock market, just like a single share. A FTSE 250 ETF is a tracker: it simply copies the index, holding (almost) all 250 companies. That means instant diversification, low fees and no need to pick winners.
Neither is “better”. They are different ingredients, and many investors hold both through a single UK or global fund.
All three below track the FTSE 250 and trade on the London Stock Exchange in pounds. Figures are taken from each provider’s published information in September 2026, so check the latest factsheet before buying.
| ETF | Ticker | Ongoing charge / TER | Income | Holdings | Launched |
|---|---|---|---|---|---|
| HSBC FTSE 250 UCITS ETF | HMCX | 0.09% | Distributing (quarterly) | ~250 | 2010 |
| Vanguard FTSE 250 UCITS ETF | VMID | 0.10% | Distributing (quarterly); an accumulating version also exists | 252 | 2014 |
| iShares FTSE 250 UCITS ETF | MIDD | 0.40% | Distributing (quarterly); trailing 12-month yield 3.15% | 237 | 2004 |
Why it stands out: a low 0.10% ongoing charge from a well-known provider, with the option of accumulating units that reinvest dividends for you. Its fund size was around £1.6bn at the end of August 2026, a sign of popularity.
Key risk: the fund is concentrated in UK mid-sized companies, so it is tied to the UK economy.
Why it stands out: the lowest published charge of the three at 0.09%, using full replication, meaning it holds the actual shares.
Key risk: it is a smaller fund (about EUR 71 million), so check the trading spread, the gap between the buy and sell price, before you deal.
Why it stands out: the longest track record (launched 2004) and a large holdings list of 237 companies, with net assets around £652m.
Key risk: at 0.40% it costs around four times as much as the cheapest options, and over decades that adds up.
Other providers also offer FTSE 250 ETFs, including Xtrackers and Amundi. Compare charges, size and whether they pay out or reinvest income.
Pros: instant diversification across roughly 250 firms; low costs; simple to buy in an ISA; UK-listed ETFs are generally exempt from the 0.5% stamp duty charged on UK shares; dividends from quarterly-paying funds.
Cons: all your eggs are in one country; mid-sized firms can be more volatile than giants in a downturn; performance has recently lagged; and there are no guarantees. A FTSE 250 fund is best as part of a wider portfolio, not your only investment.
They can be a low-cost way to own a spread of UK mid-sized companies, but they are riskier than a global fund because they concentrate on one country. They suit long-term investors who can ride out ups and downs.
Yes. These UK-listed ETFs can generally be held in a Stocks & Shares ISA; check with your platform.
Not necessarily. Mid-caps offer more exposure to the UK economy; large caps offer more global earnings. Holding both is common.
This article is for informational and educational purposes only and is not regulated financial advice. Investing involves risk, including the loss of money; ETF values can go down as well as up, and past performance is not a guide to the future. Fees, holdings and yields are as published by the fund providers at the time of writing (late September 2026) and are subject to change. Fund names are examples, not recommendations. Do your own research or speak to a regulated financial adviser before investing.
Direct to your inbox every week
New data capture form 2023
Your money-making expert. Financial journalist, TV and radio personality.

Leave a Reply