Jasmine Birtles
Your money-making expert. Financial journalist, TV and radio personality.

 Moneymagpie Team
22nd Oct 2026
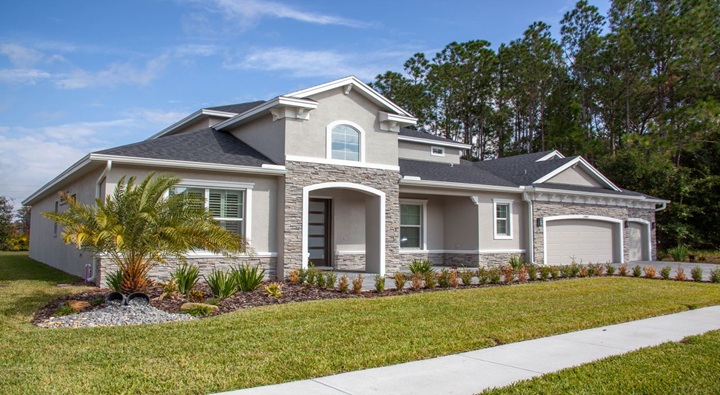
A new roof is one of those bills nobody looks forward to. It’s big, it rarely arrives at a convenient moment, and in Louisiana it can feel as though the weather is actively working against you. But roofing prices aren’t a mystery. Know the main cost drivers and you can plan ahead, compare quotes properly and avoid paying for extras you don’t need.
Roof Observations, an independent roofing consultancy that publishes state-by-state pricing, puts the average installed cost of architectural asphalt shingles in Louisiana at $5.15 per square foot in its 2026 guide. Basic 3-tab shingles come in at around $4.70. On what it treats as a typical 1,700 square foot residential roof, that works out at roughly $7,990 for 3-tab shingles and $8,755 for architectural ones. Those averages assume a moderate 6/12 pitch and already include tear-off of the old roof, underlayment, flashing and the other standard components.
Other materials from the same guide look like this:
One thing that catches people out is that roof area isn’t the same as floor area. Say you have a 2,000 square foot ranch home with an attached garage and generous eaves. The roof itself could easily measure more than the living space once overhangs and pitch are factored in. Ask every contractor for the measured roof area, usually given in “squares” (one square is 100 square feet), so you’re comparing quotes on the same footing.
Bigger roofs need more material and labour. Shape matters too. Steep slopes are slower and riskier to work on, and every valley, dormer, skylight and chimney adds cutting and flashing. Roof Observations estimates that steeper or more complex roofs can push costs up by as much as 30%.
Asphalt shingles are the cheapest upfront and by far the most common choice in Louisiana. Metal costs more but lasts longer and handles wind and heat well. Tile is heavy, so it’s worth having the roof structure checked before you fall in love with the look. The smartest comparison is cost per year of expected life rather than the headline price.
Removing an existing roof typically adds $1 to $3 per square foot, according to Roof Observations. The real wildcard is the wooden decking underneath. In a humid climate, rotten or soft boards are common, and nobody can see them until the old shingles come off. A good quote will state a price per sheet of replacement decking so you’re not hit with a surprise figure halfway through the job.
Permit requirements and fees vary between parishes and cities, so check what applies locally and confirm who is pulling the permit. Labour is a big slice of any roofing bill, and it tends to climb when demand spikes after a major storm.
Shingles with higher wind uplift ratings, enhanced nailing patterns, a sealed roof deck and upgraded underlayment all add to the cost. In most of Louisiana they’re money well spent, not least because they can bring your insurance premium down (more on that below).
Louisiana roofs have a tougher life than most. Hurricane season officially runs from June to November, and even storms that miss you directly can bring damaging winds and torrential rain. The heat and humidity are relentless too. Algae streaks are common on asphalt shingles, so algae-resistant products are worth asking about, and good attic ventilation matters for both comfort and roof life. Poor ventilation can even void some shingle warranties.
Then there’s insurance. Insurers pay close attention to roof age and condition, and hurricane deductibles are often a percentage of your dwelling coverage rather than a flat amount. Check yours before you need it, because it can be far more than people expect.
This is where Louisiana homeowners can claw back real money. The Louisiana Fortify Homes Program offers grants of up to $10,000 towards upgrading a roof to the FORTIFIED Roof standard set by the Insurance Institute for Business and Home Safety (IBHS). A few key points:
The savings don’t stop once the roof is on. Under the Louisiana Department of Insurance’s FORTIFIED benchmark discounts, which insurers must implement by January 1, 2027, a FORTIFIED Roof qualifies for a discount of 16% in the North zone, 27% in the Central zone and 29% in the South zone on the hurricane portion of a residential premium. If you’re replacing your roof anyway, the extra cost of building to the FORTIFIED standard can pay for itself over time, even if you miss out on a grant.
Prices for the same job can vary noticeably between contractors, so collect at least three written quotes. Talking to an established Louisiana roofing contractor who knows local codes, wind ratings and the FORTIFIED process will also make it much easier to spot when another quote is missing something important.
A cheap quote is only cheap if it covers the same work. Check that each one spells out:
It’s also sensible to check the contractor’s licence with the Louisiana State Licensing Board for Contractors and ask for proof of insurance.
The worst time to buy a roof is the week after a hurricane, when everyone needs one at once. If your roof is ageing but still sound, get quotes early and book work outside the post-storm rush. A planned replacement almost always costs less than an emergency one.
Homeowners insurance generally covers sudden storm damage, not general wear and tear. If a storm hits, photograph the damage, make temporary repairs to prevent further harm, keep your receipts and contact your insurer promptly. Be cautious of door-to-door “storm chasers” who turn up after big weather events, and never sign anything handing a contractor control of your claim without reading it carefully.
If savings won’t cover the full cost, compare the total you’ll repay rather than just the monthly figure. Common routes include:
If your roof is getting on in years, a dedicated savings pot started now will reduce how much you need to borrow later.
Manufacturer warranties often need registering within a set period, and some enhanced warranties only apply when the contractor is certified by the manufacturer. Keep your contract, invoices, product details and photos together. If you ever need to make a claim, sell the house or prove a FORTIFIED upgrade to your insurer, that paperwork is worth its weight in gold
Disclaimer: MoneyMagpie is not a licensed financial advisor and therefore information found here including opinions, commentary, suggestions or strategies are for informational, entertainment or educational purposes only. This should not be considered as financial advice. Anyone thinking of investing should conduct their own due diligence.
Your money-making expert. Financial journalist, TV and radio personality.