Jasmine Birtles
Your money-making expert. Financial journalist, TV and radio personality.

 Moneymagpie Team
15th Oct 2026
Most people with a stocks and shares ISA have heard the same line about spreading risk. Good advice, no doubt. But it usually ends right there, with no real explanation of what to buy, how to buy it, what it costs, or how any of it will actually perform when the rest of your portfolio drops.
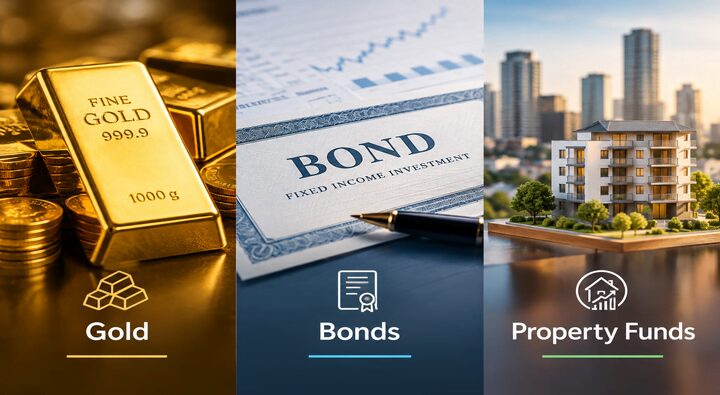
We’ll take gold, bonds and property funds one at a time here. Each one works differently. For each, we’ll cover the cheapest route in through an ISA and flag the catches, including a liquidity trap that left some property fund investors locked out of their own cash for over a year.
Gold broke through $5,500 an ounce in January for the first time ever, then gave back a big chunk of those gains over spring and summer. That tells you something. It pays no income, it doesn’t grow, and the price depends entirely on what people will pay for a safety net at any given moment.
That’s the whole point of having it. When shares crash hard, gold tends to come out the other side well ahead of equities, and it finished both 2008 and 2020 up while stock markets posted heavy losses. Expect a few rough weeks along the way, though. In the worst moments of both crashes, gold briefly sold off too as investors dumped whatever they could to raise cash. Think of it as protection across a downturn rather than a shield for every single bad day, and keep the allocation somewhere between 5% and 10% of your portfolio.
For most of the 2010s, lending money to the UK government paid almost nothing. That changed in 2023. The Bank of England hiked Bank Rate to 5.25%, and gilts became interesting again practically overnight. Rates have come back down since, with the Bank holding Bank Rate at 3.75% since December 2025, but gilt yields are still comfortably above where they’d been stuck for the previous decade.
What does that mean in real terms? A gilt fund or short-dated gilt ETF will now pay you a real income while typically moving around less than shares. Gilts also tend to rally when investors panic and run for safety. Keep in mind, though, that longer-dated bonds will lose value if rates climb again, and with inflation running at 3.1% in August, that risk is still very much on the table.
Buying a rental property means stumping up a deposit, arranging a mortgage, finding a tenant and dealing with everything that breaks. A REIT takes a few quid. Real estate investment trusts are listed companies that own portfolios of warehouses, offices, shops or flats. They’re required to pay out most of their rental income as dividends, which makes them an easy route into property without any of the hassle of actually owning a building.
Because REITs trade on the stock exchange, you can sell in seconds. Open-ended property funds work differently. They hold actual buildings, and when too many investors want their money back at the same time, the fund has to freeze withdrawals and start selling bricks and mortar, which can take months or longer. Exactly that happened after the Brexit vote in 2016, again in 2019, and right across the board in 2020. Some investors waited over a year to get out. If you want property in your portfolio, a REIT or REIT ETF will sidestep that problem entirely.
Most people haven’t started yet. The FCA’s Financial Lives survey found that 61% of adults with more than £10,000 in investible assets keep at least three-quarters of that money in cash. Access has improved, though. A decade ago, buying gold meant a bullion dealer and buying gilts meant a phone call to a stockbroker.
Today most ISA platforms list gold ETCs, gilt ETFs and REITs right alongside ordinary shares. Trading Brokers, which reviews FCA-regulated brokers for UK traders, has noted growing demand for gold, bond and commodity markets across the platforms it covers. One aspect of that demand is that buying any of the three now takes minutes through the same account that already holds your shares. Each asset comes packaged in its own type of product, though, and the packaging decides what you actually own. Here’s what the main wrappers look like:
Tax treatment matters here. Every one of these fits inside a stocks and shares ISA, so any gains and income you earn from gold ETCs, gilt funds or REITs will be completely tax-free as long as they’re held within the wrapper.
Ongoing charges matter more here than with a cheap global equity tracker. Gold ETCs typically charge between 0.1% and 0.4% a year, while some property funds will take over 1%, which adds up quickly when the underlying returns aren’t as high as equities. Check the spread too. On smaller REITs, the gap between buy and sell prices can swallow a decent chunk of your first year’s income before you’ve even noticed.
Currency is another one people miss. Most gold ETCs are priced in dollars, so even if the gold price holds steady, a strengthening pound will eat into your return when you sell. Some products offer sterling-hedged versions that remove this risk, but they’ll charge slightly more for the privilege. Read the product factsheet before you buy, because the headline charge rarely tells the full story once you factor in trading costs, currency exposure and the tracking difference between the fund and the actual asset it’s supposed to follow.
Adding gold, bonds or property to a shares-only portfolio will cost you some upside during a strong bull market. That’s the honest trade-off. When shares are climbing 15% a year, a 5% allocation to gold that’s gone nowhere will feel like dead weight, and you’ll question why you bothered.
Then a correction arrives and the answer becomes obvious. When shares drop 20%, your whole portfolio won’t drop 20% along with them, and that cushion is what you’re really paying for during the years when everything else is going up. Start with one asset class, probably a gilt fund given where yields are right now, and learn how it moves through a few different market conditions before adding anything else. The point isn’t to pick the best-performing diversifier. It’s to own something that behaves differently from shares when shares stop behaving well.
Disclaimer: MoneyMagpie is not a licensed financial advisor and therefore information found here including opinions, commentary, suggestions or strategies are for informational, entertainment or educational purposes only. This should not be considered as financial advice. Anyone thinking of investing should conduct their own due diligence.
Your money-making expert. Financial journalist, TV and radio personality.